India’s Unified Payments Interface (UPI) has successfully revolutionized the nation's commerce, onboarding millions of small merchants and consumers into the digital economy. However, the system's foundational principle—a zero-cost transaction model—has created a growing financial paradox, forcing regulators and industry players to confront the pressing question of who should pay for the world's largest real-time payments network.
The Zero-Fee Growth Engine
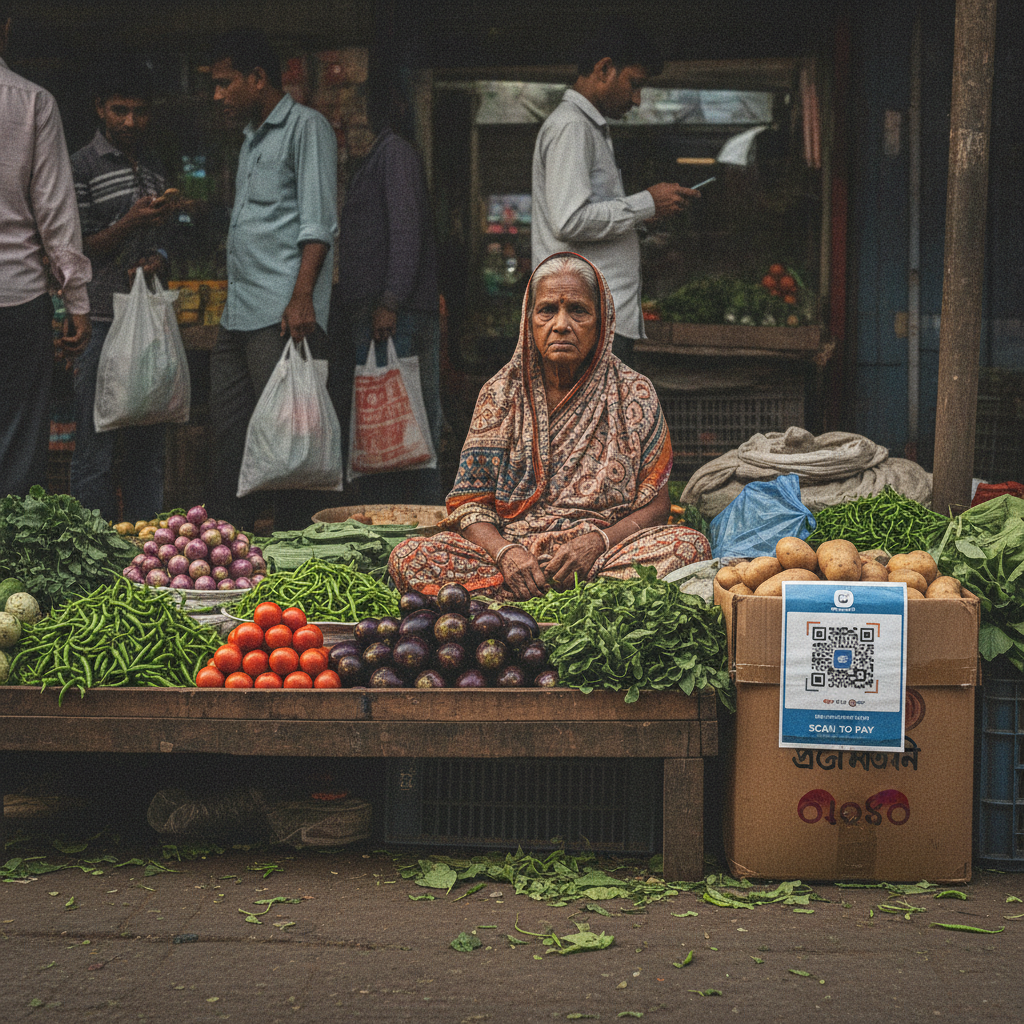
The explosive growth of UPI was directly fueled by a government mandate for a zero Merchant Discount Rate (MDR), which eliminated transaction fees for merchants. This policy spurred unprecedented adoption, making QR code-based payments a common sight from metropolitan retailers to roadside vegetable vendors. For consumers and businesses, the system offered a seamless and free alternative to cash.
Mounting Costs for Service Providers
While the no-fee structure drove adoption, it placed the entire financial burden of operating the system on banks and payment service providers. These entities incur significant costs related to technology infrastructure, security, and processing billions of transactions each month. Without a direct revenue stream from these payments, the current model is widely seen as unsustainable, creating operational strain on the very companies that facilitate the network.
The Search for a Viable Path Forward
The conversation around UPI's future now centers on establishing a financially viable framework. The Reserve Bank of India (RBI) and the National Payments Corporation of India (NPCI), the system's operator, are exploring potential revenue models. These discussions include the possibility of introducing a small, regulated fee to ensure the network can fund its own operations and future innovation without reversing its progress in financial inclusion.
Industry and Market Implications
Any move to introduce fees could fundamentally alter the digital payments landscape. For fintech companies that have struggled to monetize their UPI platforms, it could create a clear business model. However, it also presents a significant risk. Even a nominal charge could deter price-sensitive small merchants and users, potentially slowing down digital payment adoption and pushing a segment of the market back towards cash transactions. The key challenge for policymakers is to find a balance that ensures the ecosystem's financial health without alienating its vast user base. The final decision will be a critical determinant in the next phase of India's digital transformation.