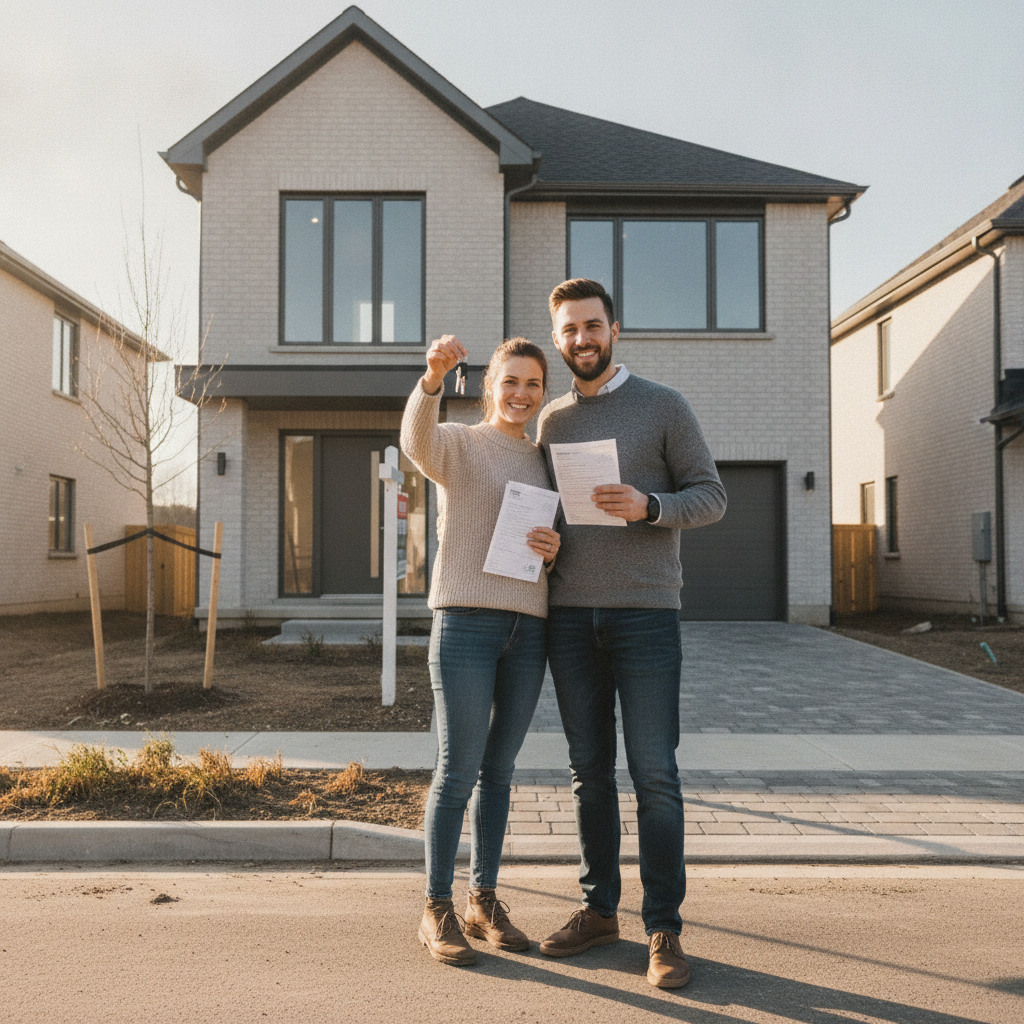
A new financial product is allowing some renters to enter the UK property market without a deposit, a significant shift in a lending landscape that has demanded substantial upfront capital for over a decade. Bronte and Jordan Charles recently purchased a three-bedroom home in Carlisle for £242,000 using a 100% mortgage from Skipton Building Society, illustrating a novel approach to the affordability crisis.
A Solution for the 'Rental Trap'
Skipton's "Track Record" mortgage is specifically designed for individuals caught in a cycle of paying high rent, which prevents them from saving for a deposit. Instead of a down payment, the lender requires applicants to provide evidence of at least 12 consecutive months of consistent rental payments. In the case of the Charles couple, their history of paying £800 per month in rent demonstrated their ability to manage their new, higher mortgage payment of £1,050.
Product Structure and Borrower Profile
The product signals a calculated return to a lending practice largely abandoned after the 2008 financial crisis. The couple secured a five-year fixed rate of 5.45% over a 35-year term. This structure provides payment stability in the medium term, but the extended loan period reflects the higher borrowing amount relative to conventional mortgages. The target demographic is clearly defined: creditworthy tenants whose rental payments prove their financial discipline and capacity for homeownership costs.
The Return of Negative Equity Risk
While offering a route onto the property ladder, 100% loan-to-value mortgages reintroduce a significant risk: negative equity. This occurs if property values fall below the outstanding mortgage balance, leaving the homeowner owing more than their asset is worth. This can severely restrict a borrower's ability to sell the property or remortgage to a more favorable rate in the future. The borrowers acknowledged their awareness of this potential vulnerability in a fluctuating housing market.
Market Implications
Skipton's initiative serves as a test case for the broader market. Its success could pressure other lenders to innovate for the renter demographic, potentially altering lending criteria for first-time buyers. However, financial regulators will be closely monitoring the performance of these loans and the associated risks, given the historical context of high loan-to-value lending. The product addresses a clear market need but its long-term viability will depend on stable property values and borrower performance.